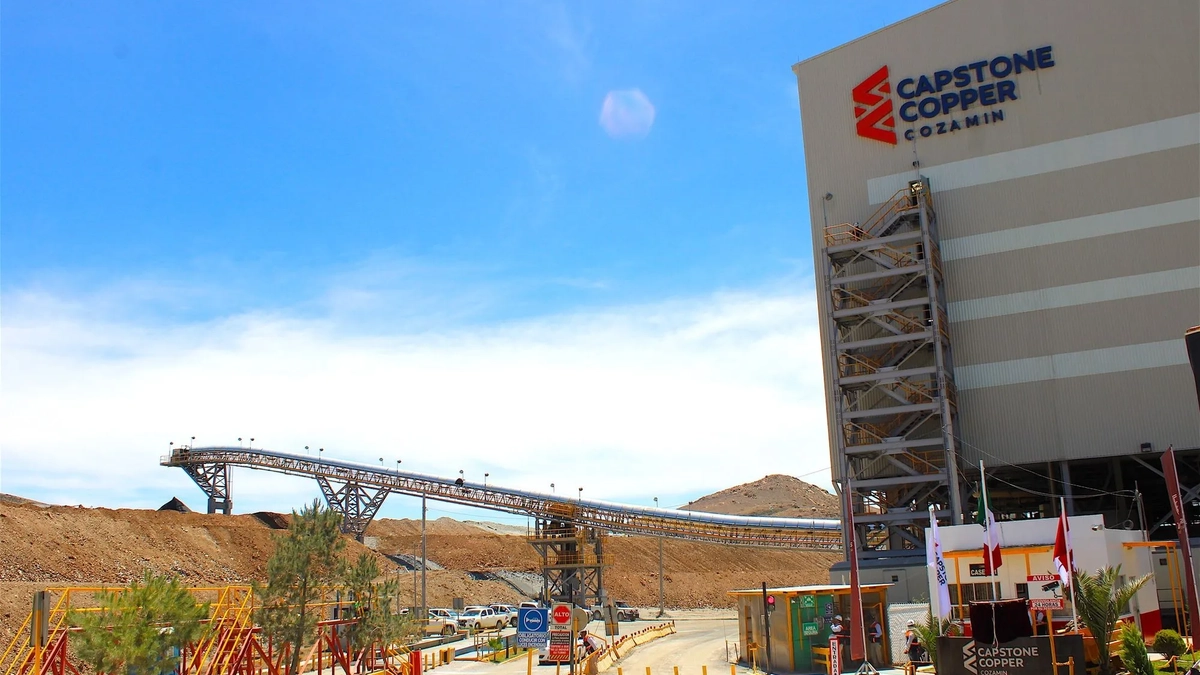
Luca Mining signed a definitive share-purchase agreement with Capstone Copper to acquire 100% of the Cozamin underground copper-silver mine in Zacatecas, Mexico. The transaction carries $290 million of upfront consideration and as much as $95 million of deferred and contingent payments.
At closing, Luca would pay $275 million in cash and issue $15 million of its common shares to Capstone. A further $35 million is due on the first anniversary, in cash or shares at Luca’s choice, while up to $60 million depends on annual copper-price thresholds during 2027, 2028 and 2029.
Cozamin has operated continuously for 20 years and has a historical reserve-based mine plan extending through 2030. Luca has not adopted that plan or the historical resource and reserve estimates as current under Canadian disclosure rules; it intends to validate the data and prepare an updated technical report after closing.
Based on consensus estimates presented by the buyer, the combination could generate about $598 million of net revenue and $223 million of operating cash flow in 2027, compared with Luca’s respective 2025 figures of $177 million and $37 million. These are forward-looking estimates, not realized results.
The funding package includes a C$155 million bought-deal placement worth about $110 million, a roughly $40 million concurrent private placement, a $125 million senior secured acquisition facility and a $25 million additional silver stream. Trafigura also provided an equity backstop of up to $75 million, subject to an ownership cap.
The four-year loan facility combines a $75 million tranche at 8.5% and a $50 million tranche at the secured overnight financing rate plus 4.9%. Luca will also issue warrants, hedge 25% of forecast Cozamin copper sales for 36 months from 2027 and deliver an additional share of refined silver under the new stream.
Closing is expected in the fourth quarter of 2026 and requires approvals from Mexico’s federal antitrust authority and the TSX Venture Exchange, plus customary conditions. Until those requirements and the financing conditions are satisfied, the signed agreement is not the same as completed ownership transfer.
The transaction would add a cash-generating asset and greater copper exposure to Luca’s Mexican portfolio, but integration, mine-life extension and the projected financial gains remain execution questions. Historical estimates must be verified, and the copper-linked consideration also means the ultimate price may vary.