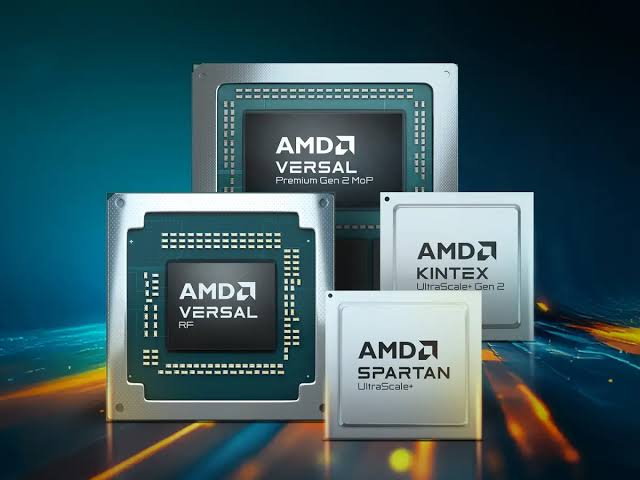
AMD’s large artificial-intelligence chip agreements with OpenAI and Meta are beginning to affect its reported earnings before the customers have exercised any shares. The company’s filing shows a $1.2 billion warrant liability at September 26 and a $1.2 billion noncash quarterly charge, principally from remeasuring that liability as AMD’s share price and the estimated probability of meeting exercise conditions increased.
The commercial arrangements are unusually large. OpenAI and Meta each received a warrant to buy up to 160 million AMD common shares for $0.01 apiece. The warrants were issued alongside multi-year agreements under which each customer intends to deploy up to six gigawatts of AMD data-centre GPUs, with early deployments based on the Instinct MI450 product family.
The headline share entitlement is not immediately outstanding stock. Warrants vest in tranches tied to specified GPU purchase milestones, share-price targets and technical and commercial conditions. OpenAI’s warrant also has relative stock-performance thresholds. At September 26, no warrant share had vested, become exercisable, been exercised, forfeited or expired.
Accounting begins earlier than legal dilution. AMD measures the fair value attributable to qualifying customer revenue and recognises changes through earnings while the instruments remain liabilities. The weighted-average value rose from $14.25 per share at grant to $178.58 at quarter-end. The filing records $1.179 billion of net noncash warrant impact in the nine-month cash-flow reconciliation.
A separate $4.5 billion of unrecognised grant-date value remains attached to unvested warrants and would be recorded as a reduction of revenue as qualifying sales are recognised. This means the customer incentives can influence both other income or expense through remeasurement and reported revenue through the original value allocation. Neither effect is the same as cash leaving the company in the quarter.
The economic trade-off is customer commitment versus shareholder dilution. If purchase, technical and market conditions are satisfied, OpenAI and Meta could acquire a combined maximum of 320 million shares at nominal exercise cost. Against roughly 1.64 billion shares outstanding, that maximum is material, although actual dilution depends on vesting, exercise and future share count.
AMD agreed to sell Meta up to $60 billion of chips over five years, while the OpenAI agreement also targets a major multi-year deployment. The incentives can strengthen adoption of AMD software and accelerators as customers seek an alternative to Nvidia. They also create a circular relationship in which large customers receive equity upside from purchases they help generate.
The correct test is therefore broader than the $1.2 billion charge. Investors need qualifying revenue, gross margin after incentive allocation, purchase milestones, cash collection, competitive performance and shares ultimately issued. The charge is noncash and valuation-sensitive, but the potential dilution is economically real if conditions are met; conversely, the full 320 million shares are not yet earned or outstanding.