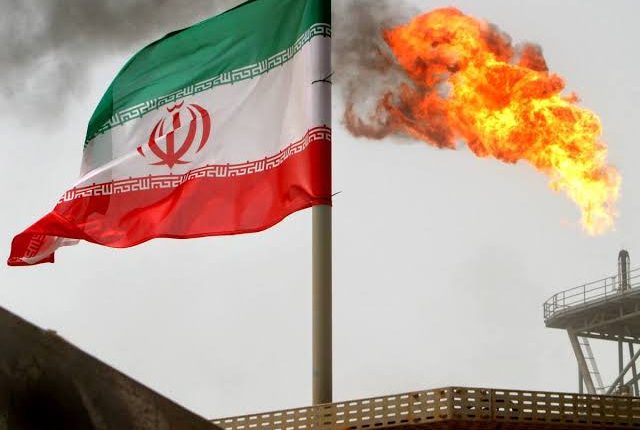
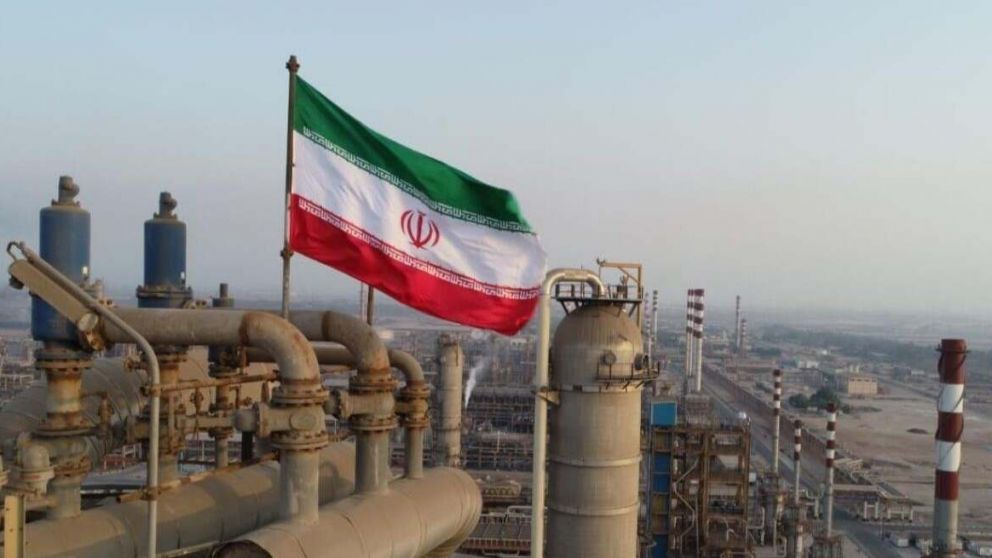
Oil prices fell by nearly $2 a barrel in volatile November 4 trading as investors recalibrated the immediate risk of a new escalation in the US-Israeli war with Iran. Brent futures declined $1.92, or 1.85%, to $101.68 at 13:10 GMT, while West Texas Intermediate lost $1.75, or 1.82%, to $94.34. Both contracts had traded about $1 higher earlier.
The reversal followed the US midterm election, in which Democrats won both chambers of Congress. Markets interpreted the result and President Donald Trump’s statement that there were no immediate plans to strike Iran as lowering the probability of near-term escalation. That is a political inference, not a peace agreement, and the executive retains significant operational authority.
Diplomacy remains incomplete. Qatar intensified mediation, but a senior Iranian official said the United States and Iran remained far from an agreement. Iran’s supreme leader, Mojtaba Khamenei, argued that US hostility would persist regardless of the party in power. Traders therefore reduced the immediate premium without removing longer-term conflict risk.
Physical flows provide a second signal. Gulf exports of crude, condensate and refined products excluding LPG averaged 17.1 million barrels a day in October, down from 18.9 million in September and still only about three quarters of pre-war volumes. Recovering crude shipments have begun to pressure physical cargo prices, but the sequence is uneven.
Refined-product exports remain notably weaker. That distinction matters because more crude reaching refineries can normalise feedstock costs while gasoline, diesel and jet-fuel availability still constrains consumer prices. Relief at the pump depends on refinery operations, product shipping, inventories and regional distribution, not crude flows alone.
US inventory data pointed in the opposite direction. An industry estimate showed crude stocks fell 5.27 million barrels in the week ended October 30, whereas analysts had expected an 880,000-barrel increase. Gasoline inventories rose 1.43 million barrels and distillates fell 1.19 million. The report was preliminary ahead of official government data.
The contracts had settled at nearly four-week lows in the prior session as traders also monitored possible diplomacy around Ukraine. At prices above $100 for Brent, each geopolitical headline affects inflation, transport costs and central-bank expectations. Volatility can therefore persist even when the direction of the daily close is lower.
A durable decline would require a credible ceasefire path, sustained recovery of crude and product exports, reliable refinery throughput and inventories consistent with comfortable supply. The November 4 quotations are time-specific and do not prove that war risk has disappeared. They show only that the market assigned less weight to an immediate strike at that moment.