Adani Ports and Special Economic Zone agreed to buy 100% of Netherlands-headquartered Evos from Igneo Infrastructure Partners. The proposed all-cash transaction assigns Evos an enterprise value of €2.56 billion, equivalent to about $2.88 billion, and an equity value of €1.18 billion. Those figures measure different layers of the deal: enterprise value includes net debt and similar claims, while equity value is the amount attributable to the seller.
Evos operates eight port-based liquid-storage terminals in the Netherlands, Germany, Spain, Belgium and Malta. The platform has 6.3 million cubic metres of storage capacity, 452 tanks and 63 vessel and barge berths, and handled 37 million metric tons in 2025. Its locations span the Amsterdam-Rotterdam-Antwerp hub, Hamburg and Mediterranean gateways, with pipelines serving Schiphol airport and the Central Europe system.
The target reported €392 million of revenue and €219 million of EBITDA in 2025, a 56% margin. The agreed enterprise value represents 11.7 times that EBITDA. Average commercial occupancy is described as 99%, while take-or-pay and inflation-linked contracts support cash-flow visibility. These historical and contractual metrics strengthen the investment case but do not eliminate renewal, counterparty or volume risk.
Adani Ports plans to fund the acquisition with debt. MUFG has underwritten financing commitments of up to €2.8 billion. On a pro forma basis, management puts combined net debt to EBITDA at 2.76 times and expects roughly 2.5 times by fiscal 2027. The decline is a forecast dependent on earnings delivery, cash generation and the absence of additional leverage.
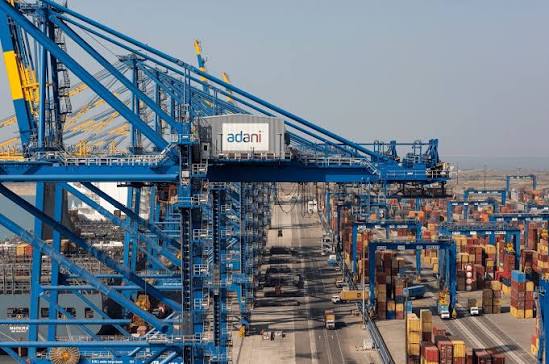
Strategically, the deal gives India’s largest private port operator its first large European liquids platform and expands its network to 28 ports and terminals in ten countries. It also diversifies Adani beyond containers and dry bulk into conventional fuels, chemicals and transition products including sustainable aviation fuel, biofuels, methanol and bioethanol.
The energy-transition thesis is not automatic. Existing tanks and pipelines may require investment, certification or conversion for new products, while European fuel demand, regulation and carbon policy can change utilisation. Evos’s current profitability comes from a mixed portfolio, so future value depends on managing legacy hydrocarbons alongside lower-carbon products rather than replacing one overnight.
The acquisition is signed but not closed. Regulatory approvals, other customary conditions and consultation with works councils must still be completed. Until then, Adani does not control Evos. Shares closed 1.3% lower after the announcement, a market reaction that may reflect leverage, price and execution concerns rather than a definitive judgment on long-term industrial logic.
The next evidence will be clearance in the relevant jurisdictions, final financing terms, the closing date, any purchase-price adjustments and post-deal operating performance. Investors should compare realised EBITDA, occupancy, contract renewal and leverage against management’s assumptions. The €2.56 billion headline establishes scale; it does not by itself prove integration success or deleveraging.