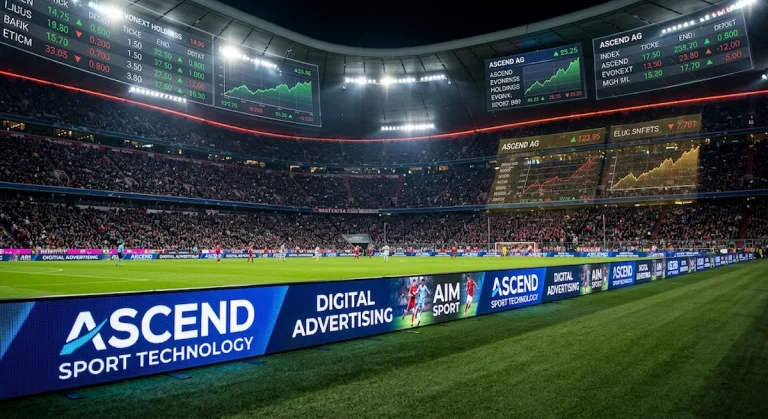
EvoNext Holdings and Ascend Sport Technology signed the formal merger agreement that advances their planned combination from the binding transaction agreement announced on October 12. The structure is a statutory merger in which Ascend’s operating business will be contributed against newly issued EvoNext shares. The surviving listed company would adopt the Ascend Sport Technology name and remain traded on the SIX Swiss Exchange.
Signing does not complete the transaction. Extraordinary general meetings of both companies are scheduled for December 3, and the resolutions become effective only if shareholders approve the merger agreement. EvoNext’s board recommends approval unanimously, but customary closing conditions and the publication of legally required merger and offering documents still separate the agreement from completion.
The capital-markets component is substantial. After the merger, EvoNext plans a share placement of up to CHF 220 million, including a 10% greenshoe of secondary shares, at an expected price of CHF 2.50 per share. The offer is intended to be predominantly secondary, with a smaller primary issuance to fund growth, strategic initiatives and general corporate purposes.
That composition matters because secondary proceeds go to selling shareholders rather than directly to the company. The primary portion alone adds corporate capital. The placement targets a free float of about 40% and a broader institutional shareholder base, but demand, final size and allocation will only be known after marketing and bookbuilding. Current EvoNext shareholders are expected to own roughly 3.8% of the combined entity.
Lock-ups are designed to manage post-listing supply. Former Ascend shareholders, management, directors and certain EvoNext holders will have half of the relevant shares restricted for 12 months and the other half for 24 months, subject to customary exceptions. Those arrangements can reduce immediate selling pressure, but they do not eliminate future dilution, liquidity or valuation risk.
Ascend reports operations across digital signage, virtual advertising overlays, sponsorship marketplaces, audience intelligence, streaming and analytics. It says it serves more than 100 rights holders and 500 brands and broadcasters in over 20 countries, supports 12 leading leagues and has worked on more than 10,000 matches. These reach metrics describe the platform but do not substitute for customer concentration or contract-renewal data.
For the year ended June 2026, Ascend reports about CHF 44 million in net revenue and CHF 25 million in EBITDA, a 57% margin. It targets doubling revenue over four years, around 10% growth in 2026/27 and medium-term EBITDA margins near 50%. Management expects EBITDA to remain broadly flat this year as public-company functions add cost and does not currently plan a dividend.
The merger offers Ascend a public listing and access to capital while giving EvoNext shareholders a small position in an operating sports-technology group. Execution remains the test: shareholder votes, prospectus, bookbuilding, closing, customer retention, tournament-driven revenue timing, capital expenditure and disciplined acquisitions. Until those steps occur, CHF 220 million is a maximum placement plan, not capital already raised.