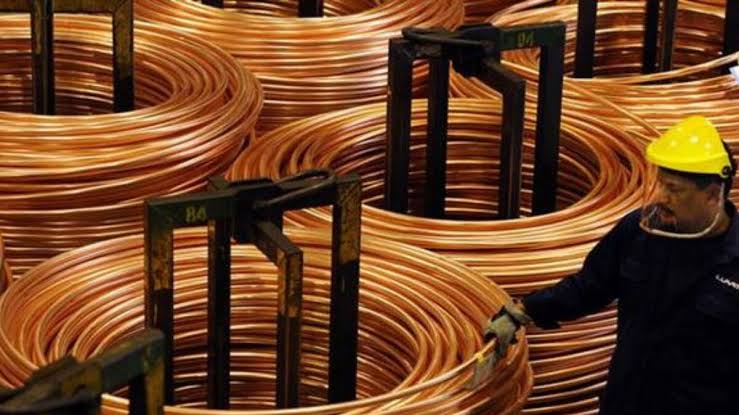
Copper prices weakened at the end of October as macroeconomic risk aversion outweighed evidence of tight immediate supply. Three-month copper on the London Metal Exchange fell 0.9% to about $14,227 a tonne by late morning, after touching a one-week low of $14,216. The contract was heading for an October decline of roughly 1%, its first monthly loss since June after three consecutive advances.
The retreat followed a record of $14,875 a tonne reached in September. Investors were reducing exposure to growth-sensitive assets as heavy spending on artificial-intelligence infrastructure raised questions about returns, oil prices remained elevated and money moved toward bonds. Copper is particularly sensitive to that combination because its price reflects both industrial demand and the cost of holding a dollar-denominated cyclical asset.
The financial signal, however, did not match the physical market. The premium for cash copper over later LME contracts remained elevated, a backwardated structure that rewards holders of immediately deliverable metal. Months of shipments into United States warehouses had reduced availability in traditional trading hubs, so weaker futures did not mean that consumers could easily source nearby units.
China provided a second sign of tightness. The Yangshan premium paid for imported copper was around $205 a tonne, close to a 13-year high. Domestic scrap supply was also constrained. A high import premium can indicate that buyers are willing to pay above international benchmarks to secure material, although it does not by itself prove that final manufacturing demand is accelerating.
Supply risk remained visible at Oyu Tolgoi in Mongolia, one of the world’s important copper assets. Underground operations were paused after a seismic event. The operator later described a progressive restart following safety reviews and said a local rockfall caused no structural damage; two workers sustained non-life-threatening injuries. The episode therefore created operational uncertainty without establishing a long shutdown or a quantified production loss.
The split between falling benchmark prices and strong physical premiums matters for producers, smelters and manufacturers. Miners receive a lower reference price if the decline persists, while fabricators can still face expensive prompt material and difficult procurement. Smelters must also manage treatment charges, concentrate availability and inventory location, none of which is captured fully by the headline futures quote.
Other base metals showed a mixed market rather than a uniform industrial collapse. Tin fell 1.9% to about $48,505 a tonne after touching a six-month low, even as its cash premium reached the highest level since April 2024 and Indonesian refined-tin exports declined. Aluminum and lead were broadly steady, zinc eased slightly and nickel edged higher.
The next direction will depend on whether physical scarcity persists long enough to overcome risk-off positioning. Traders will watch LME spreads and stocks, Chinese import premiums, scrap flows, the Oyu Tolgoi restart and actual factory orders. October’s expected monthly loss is a meaningful break in momentum, but the strong nearby premiums caution against reading it as evidence of abundant supply.