Transurban agreed to pay A$4.5 billion in cash for Canada Pension Plan Investment Board interests in three major Sydney toll roads. The transaction covers a 25% stake in NorthWestern Roads Group, owner of Westlink M7 and NorthConnex, and a 10.5% stake in Sydney Transport Partners, which owns WestConnex.
If completed, Transurban’s interest in NorthWestern Roads Group would rise from 50% to 75%, while its WestConnex holding would increase from 50% to 60.5%. The company would gain greater economic exposure and voting influence, but the roads would continue to have other institutional co-owners.
The parties have signed an acquisition agreement, not completed the transfer. Transurban expects closing in the next calendar year, subject to competition clearance and other customary conditions. Until those requirements are met, CPPIB remains the owner of the stakes being sold.
Transurban plans to fund the initial payment with committed debt facilities and refinance them into longer-term borrowings over time. It said no equity raising is required. That structure avoids immediate dilution for security holders but increases leverage and exposes the economics to refinancing costs.
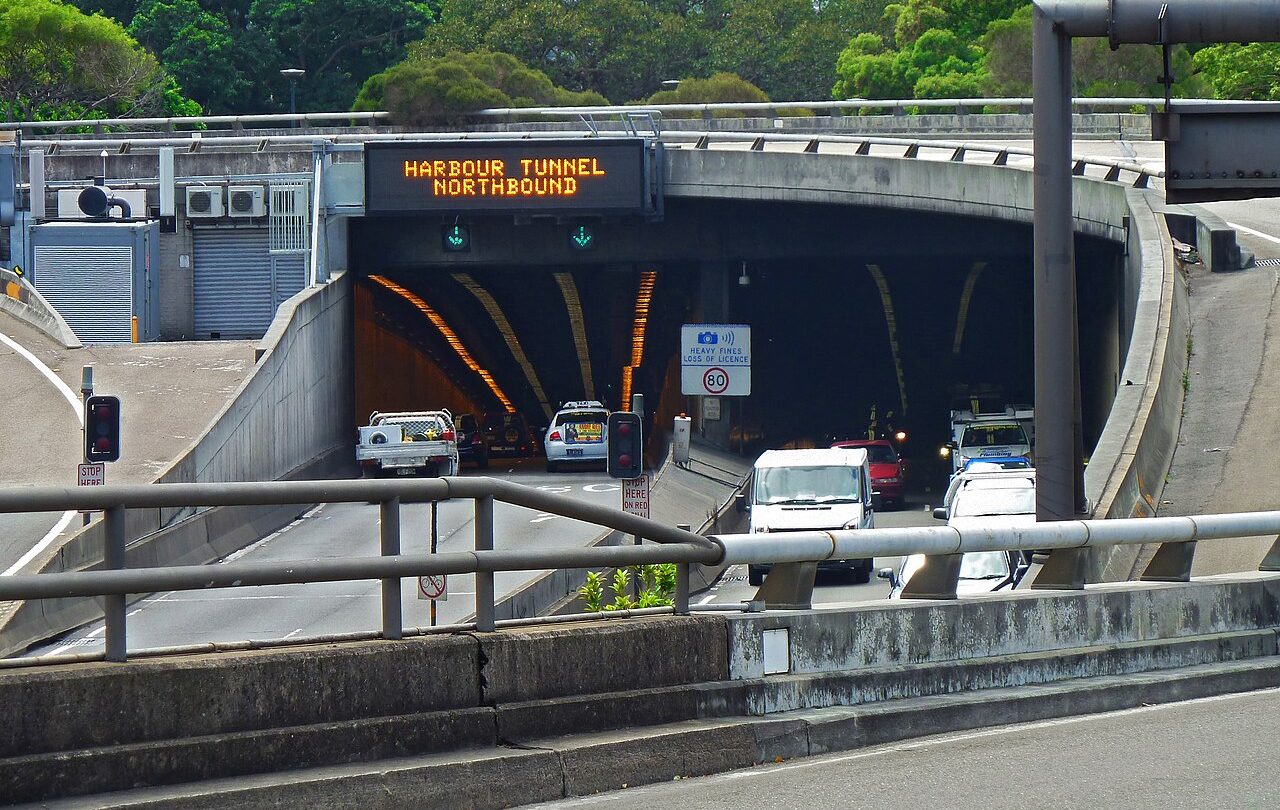
Management expects the purchase to add value and deliver growing accretion to free cash per security over the medium and long term. Those are company forecasts rather than realised returns. The projected benefit is supported partly by the future addition of M5 West to the WestConnex concession and the opening of the Western Harbour Tunnel.
The seller will receive gross proceeds of about A$4.5 billion and exit these Australian toll-road investments. CPPIB first invested in Westlink M7 in 2010, helped finance NorthConnex in 2014 and acquired its WestConnex interest in 2018, making the sale a portfolio reallocation after years of ownership.
Transurban said the ownership change itself would not alter toll charges. Pricing remains governed by concession contracts and public-policy arrangements. The acquisition was announced after a separate agreement with the New South Wales government on toll reform, but buying the stakes does not by itself rewrite those rules.
The strategic case is deeper control over a connected Sydney network; the financial test is whether future traffic, concession additions and cash generation outweigh a large debt-funded purchase at elevated borrowing costs. Regulatory approval, closing and subsequent refinancing therefore remain distinct milestones.