Shell Australia signed an agreement to sell its 16.67% non-operated interest in Western Australia’s North West Shelf project to wholly owned subsidiaries of Abu Dhabi-based XRG. The base consideration is $1.45 billion, subject to customary adjustments, with an additional payment linked to an undisclosed milestone. The transaction is agreed but not completed.
The interest extends beyond a simple share in LNG output. It includes associated upstream fields, pipeline and midstream infrastructure, varying interests in petroleum and pipeline titles, project agreements, offtake arrangements, project companies and CNOOC-related joint ventures. These interconnected rights make the asset package operationally and legally broader than the headline percentage.
The deal has an effective economic date of January 1, 2026, while legal closing is expected in 2027 after regulatory approvals and other conditions precedent. An effective date typically governs economic benefits and costs between signing and completion, but the final settlement still depends on contractual adjustments and the transaction actually closing.
XRG will also assume decommissioning obligations and provide security for them. That transfer matters because mature offshore fields and processing systems can carry large future abandonment, remediation and monitoring costs. The $1.45 billion base price therefore cannot be evaluated independently from liabilities transferred, contingent payments and working-capital or other closing adjustments.
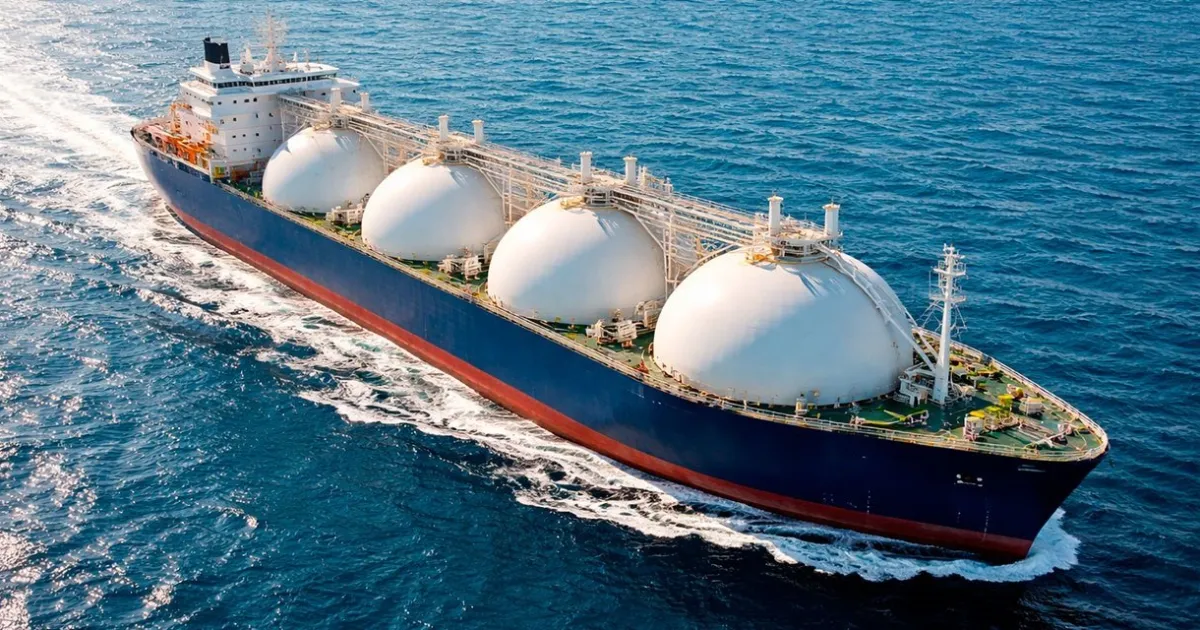
North West Shelf is an integrated LNG and domestic-gas complex operated by Woodside and held through several joint ventures with Chevron, BP, MIMI, CNOOC and others. It has 14.3 million tonnes a year of liquefaction capacity and XRG cites about 4.4 trillion cubic feet equivalent of remaining resources. This will be XRG’s first Australian LNG investment.
Production from the original fields is declining, leaving spare capacity at the Karratha Gas Plant. The project is shifting toward a mixed model that processes its own resources and third-party gas for a toll. That transition can extend infrastructure life, but it depends on securing external feedgas, commercial tariffs, environmental permissions and alignment among multiple joint-venture owners.
Shell describes the sale as a move from a mature non-operated asset toward advantaged integrated-gas positions. It still operates QGC and Prelude FLNG in Australia, is developing Crux and participates in Arrow Energy and Gorgon. Globally it targets annual LNG-sales growth of 4% to 5% through 2030, so the disposal is portfolio rotation rather than withdrawal from LNG.
For XRG, the acquisition adds immediate production, export infrastructure and proximity to Asia-Pacific customers. The investment test is whether tolling and future upstream supply offset natural decline and decommissioning costs. Evidence will be regulatory clearance, final adjusted consideration, transferred security, feedgas contracts and 2027 completion—not the signed headline alone.