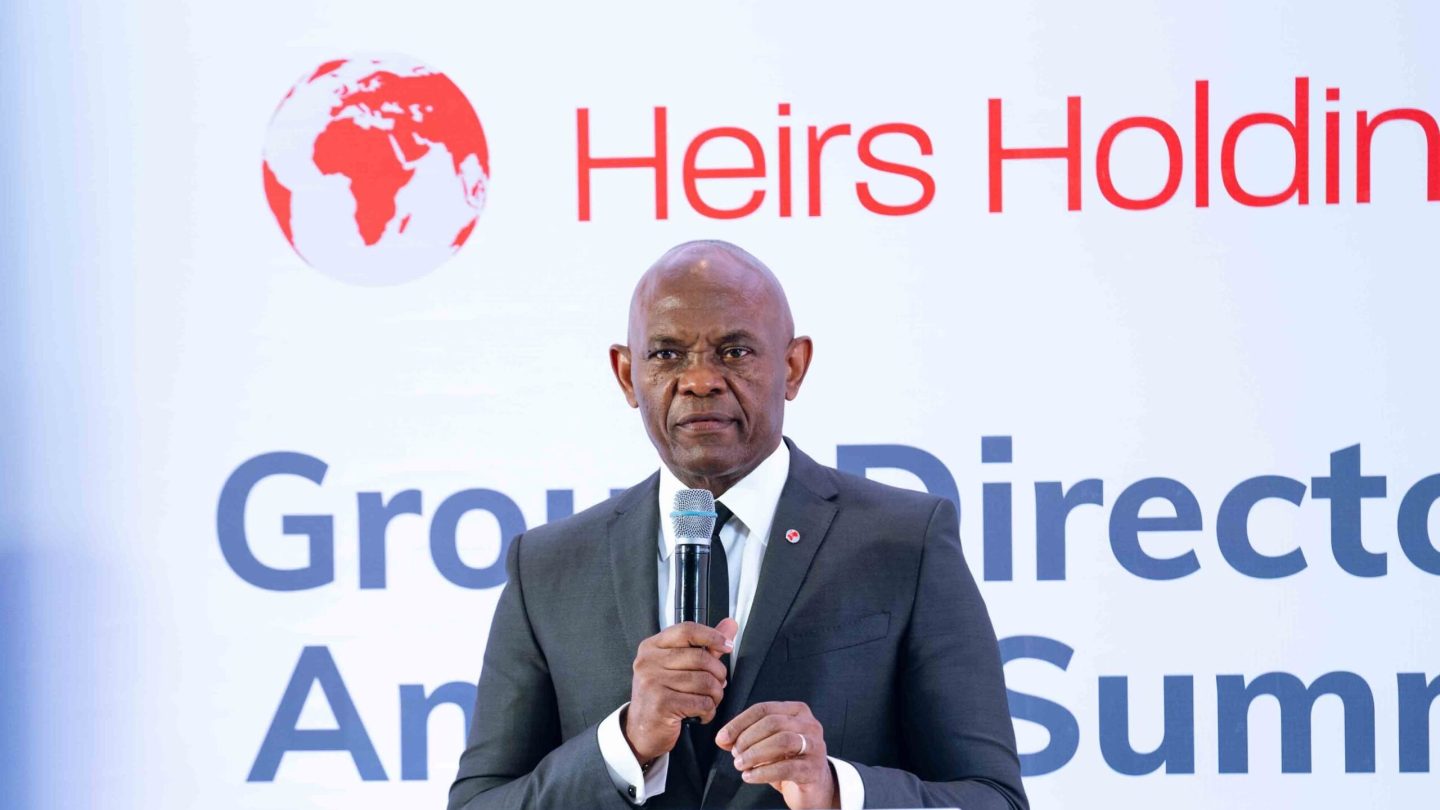
Heirs Energies, controlled by Nigerian investor Tony Elumelu, purchased 5,888,341 ordinary shares in Seplat Energy on November 16. The shares were acquired on the London Stock Exchange at £9 each, giving a disclosed transaction value of approximately £53.0 million. The reported ₦98 billion figure is a currency conversion, not the settlement denomination.
After the purchase, Heirs Energies directly held 33,832,208 shares. Together, Heirs Energies and Heirs Holdings controlled 132,288,341 shares, equal to a 22.05% voting interest based on Seplat’s 599,944,561 issued shares. The group is the largest shareholder, but 22.05% is not majority ownership or legal control by itself.
The acquisition added roughly one percentage point to the group’s position. It followed a September 30 purchase of six million shares, which had raised the combined stake to 21.07%. The two successive transactions show continued capital deployment rather than a single isolated portfolio adjustment.
Elumelu’s main entry dates to December 2025, when Heirs Energies agreed to buy Maurel & Prom’s 20.07% holding, or about 120.4 million shares, for roughly US$500 million at 305 pence per share. Afreximbank and Africa Finance Corporation supported that acquisition, adding financing relationships to the ownership story.
Seplat’s rally has transformed the market value of the position. Its Nigerian shares closed at ₦16,241.90 on November 16, compared with ₦5,809 at the end of 2025. Estimates place the group’s total stake near US$1.6 billion, but that is a mark-to-market value that can change and is not realised cash profit.
The purchase also intersects with governance. Elumelu joined Seplat’s board as a non-executive director in January 2026 and is scheduled to become chair on January 1, 2027, succeeding Udoma Udo Udoma. A larger holding increases economic alignment and influence, while related-party disclosure and independent oversight remain important.
Seplat operates substantial Nigerian oil and gas assets, so the stake concentrates exposure to production, prices, operating execution, regulation and energy policy. The appreciation that made the investment valuable also raises the cost of adding shares. Buying at £9 does not guarantee that recent market gains will persist.
The next evidence will be settlement, subsequent ownership notices, board transition, dividend policy and Seplat’s operating results. Investors should distinguish three numbers: the £53 million purchase cost, the approximate ₦98 billion conversion and the estimated US$1.6 billion value of the entire combined holding. They describe different economic concepts.