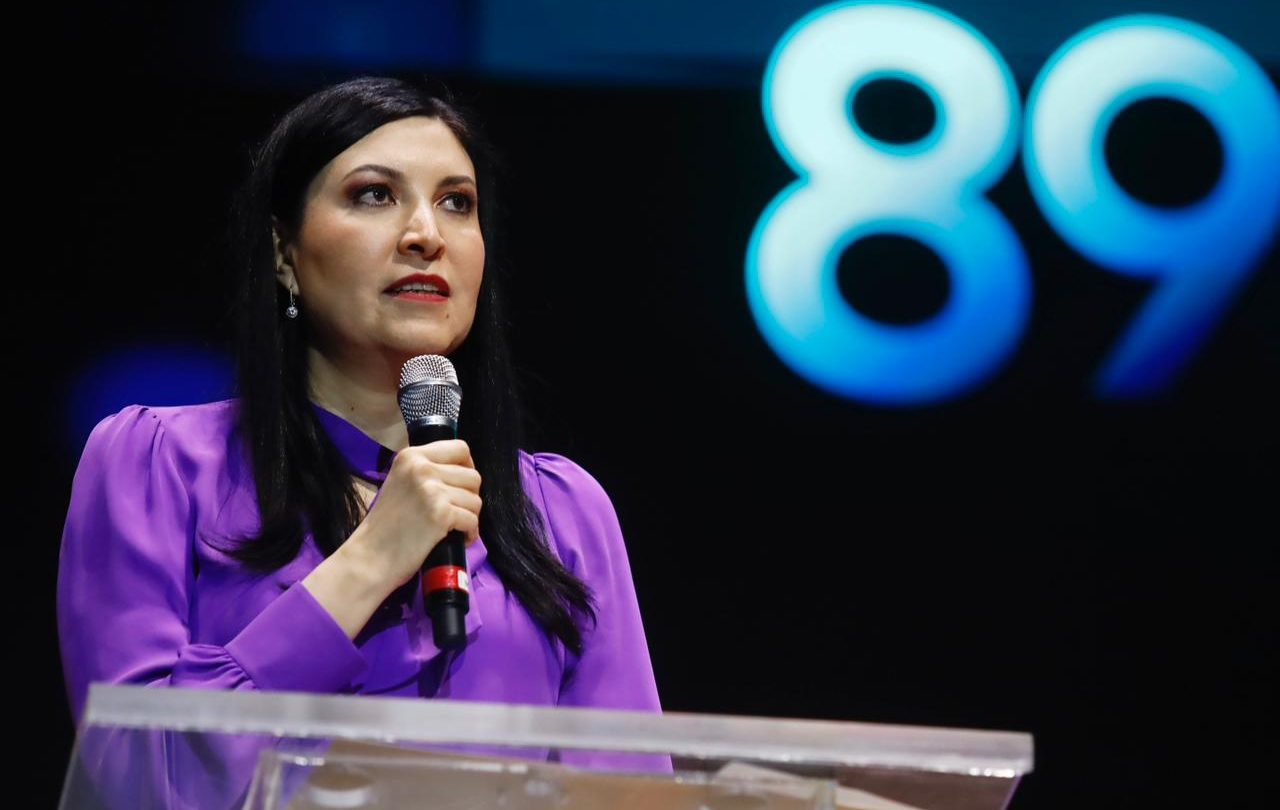
Banco de México cut its benchmark interest rate by 25 basis points to 6.25% in a divided decision that surprised a market largely expecting no change. Governor Victoria Rodríguez and deputies Gabriel Cuadra and Omar Mejía supported the reduction, while Galia Borja and Jonathan Heath voted to keep 6.50%. The narrow 3–2 result exposes a genuine disagreement over how restrictive policy must remain.
The majority said disinflation had continued, demand pressures were not evident and economic slack should limit the pass-through from a weaker peso to consumer prices. It also argued that previously imposed monetary restriction is still operating. The bank described the move as a discrete adjustment rather than the start of a mechanical sequence of cuts.
Forward guidance was therefore as important as the reduction. The board said keeping the new rate for a prolonged period would support convergence toward the 3% inflation target and help manage external macroeconomic risks. That language closes the door to assuming another cut in December, although every future decision remains conditional on prices, expectations, activity and the exchange rate.
The inflation data make the decision controversial. Headline inflation rose from 3.42% in the first half of September to 3.62% in the first half of October. Core inflation eased only marginally from 3.79% to 3.78%. The bank raised its fourth-quarter forecasts for both headline and core inflation to 3.7%, while still projecting convergence to target in the fourth quarter of 2027.
Growth and currency signals also complicate the case for easing. The economy expanded in the third quarter, and a private survey raised the 2026 growth consensus to 1.8% from 1.4%. The peso had depreciated since the September decision. Banxico nevertheless expects slack throughout the forecast horizon and sees downside risks to activity, implying current growth may not be durable or broad enough to generate demand inflation.
The risk map runs both ways. Persistent core inflation, further peso depreciation, trade-policy disruptions, geopolitical conflicts, climate events and cost shocks could push prices higher. Weaker growth in Mexico or the United States, lower cost pressure or peso appreciation could pull them lower. The cut reflects the majority’s weighting of those probabilities, not proof that inflation risk has disappeared.
Market economists questioned whether a cut is consistent with above-trend recent growth, services inflation, a weaker currency and higher internal forecasts. The dissenting votes reinforce that concern. Yet a 6.25% nominal rate remains restrictive relative to current inflation, and the prolonged-hold signal can preserve real tightening if inflation falls as forecast.
The minutes due November 19 will show how each member assessed slack, exchange-rate transmission and the balance of risks. The final scheduled decision of 2026 is December 17. The test will be inflation releases, wage and services dynamics, the peso, activity and expectations—not the surprise itself. A pause becomes credible only if data support the promised convergence.